Friday, August 7, 2026 / by Ryan Huemmer
New Fannie Mae and Freddie Mac Condo Rules: What Dane County Condo Buyers and Sellers Need to Know
If you're buying, selling, or already own a condo in the Madison area, new lending rules that took effect August 3, 2026 are about to change how that mortgage gets approved. Fannie Mae and Freddie Mac, which guarantee roughly 70% of the mortgages originated in the U.S., have eliminated the "shortcut" review process that many condo buildings used to qualify for financing. Here's what changed, why, and what it means for you.
What Changed on August 3
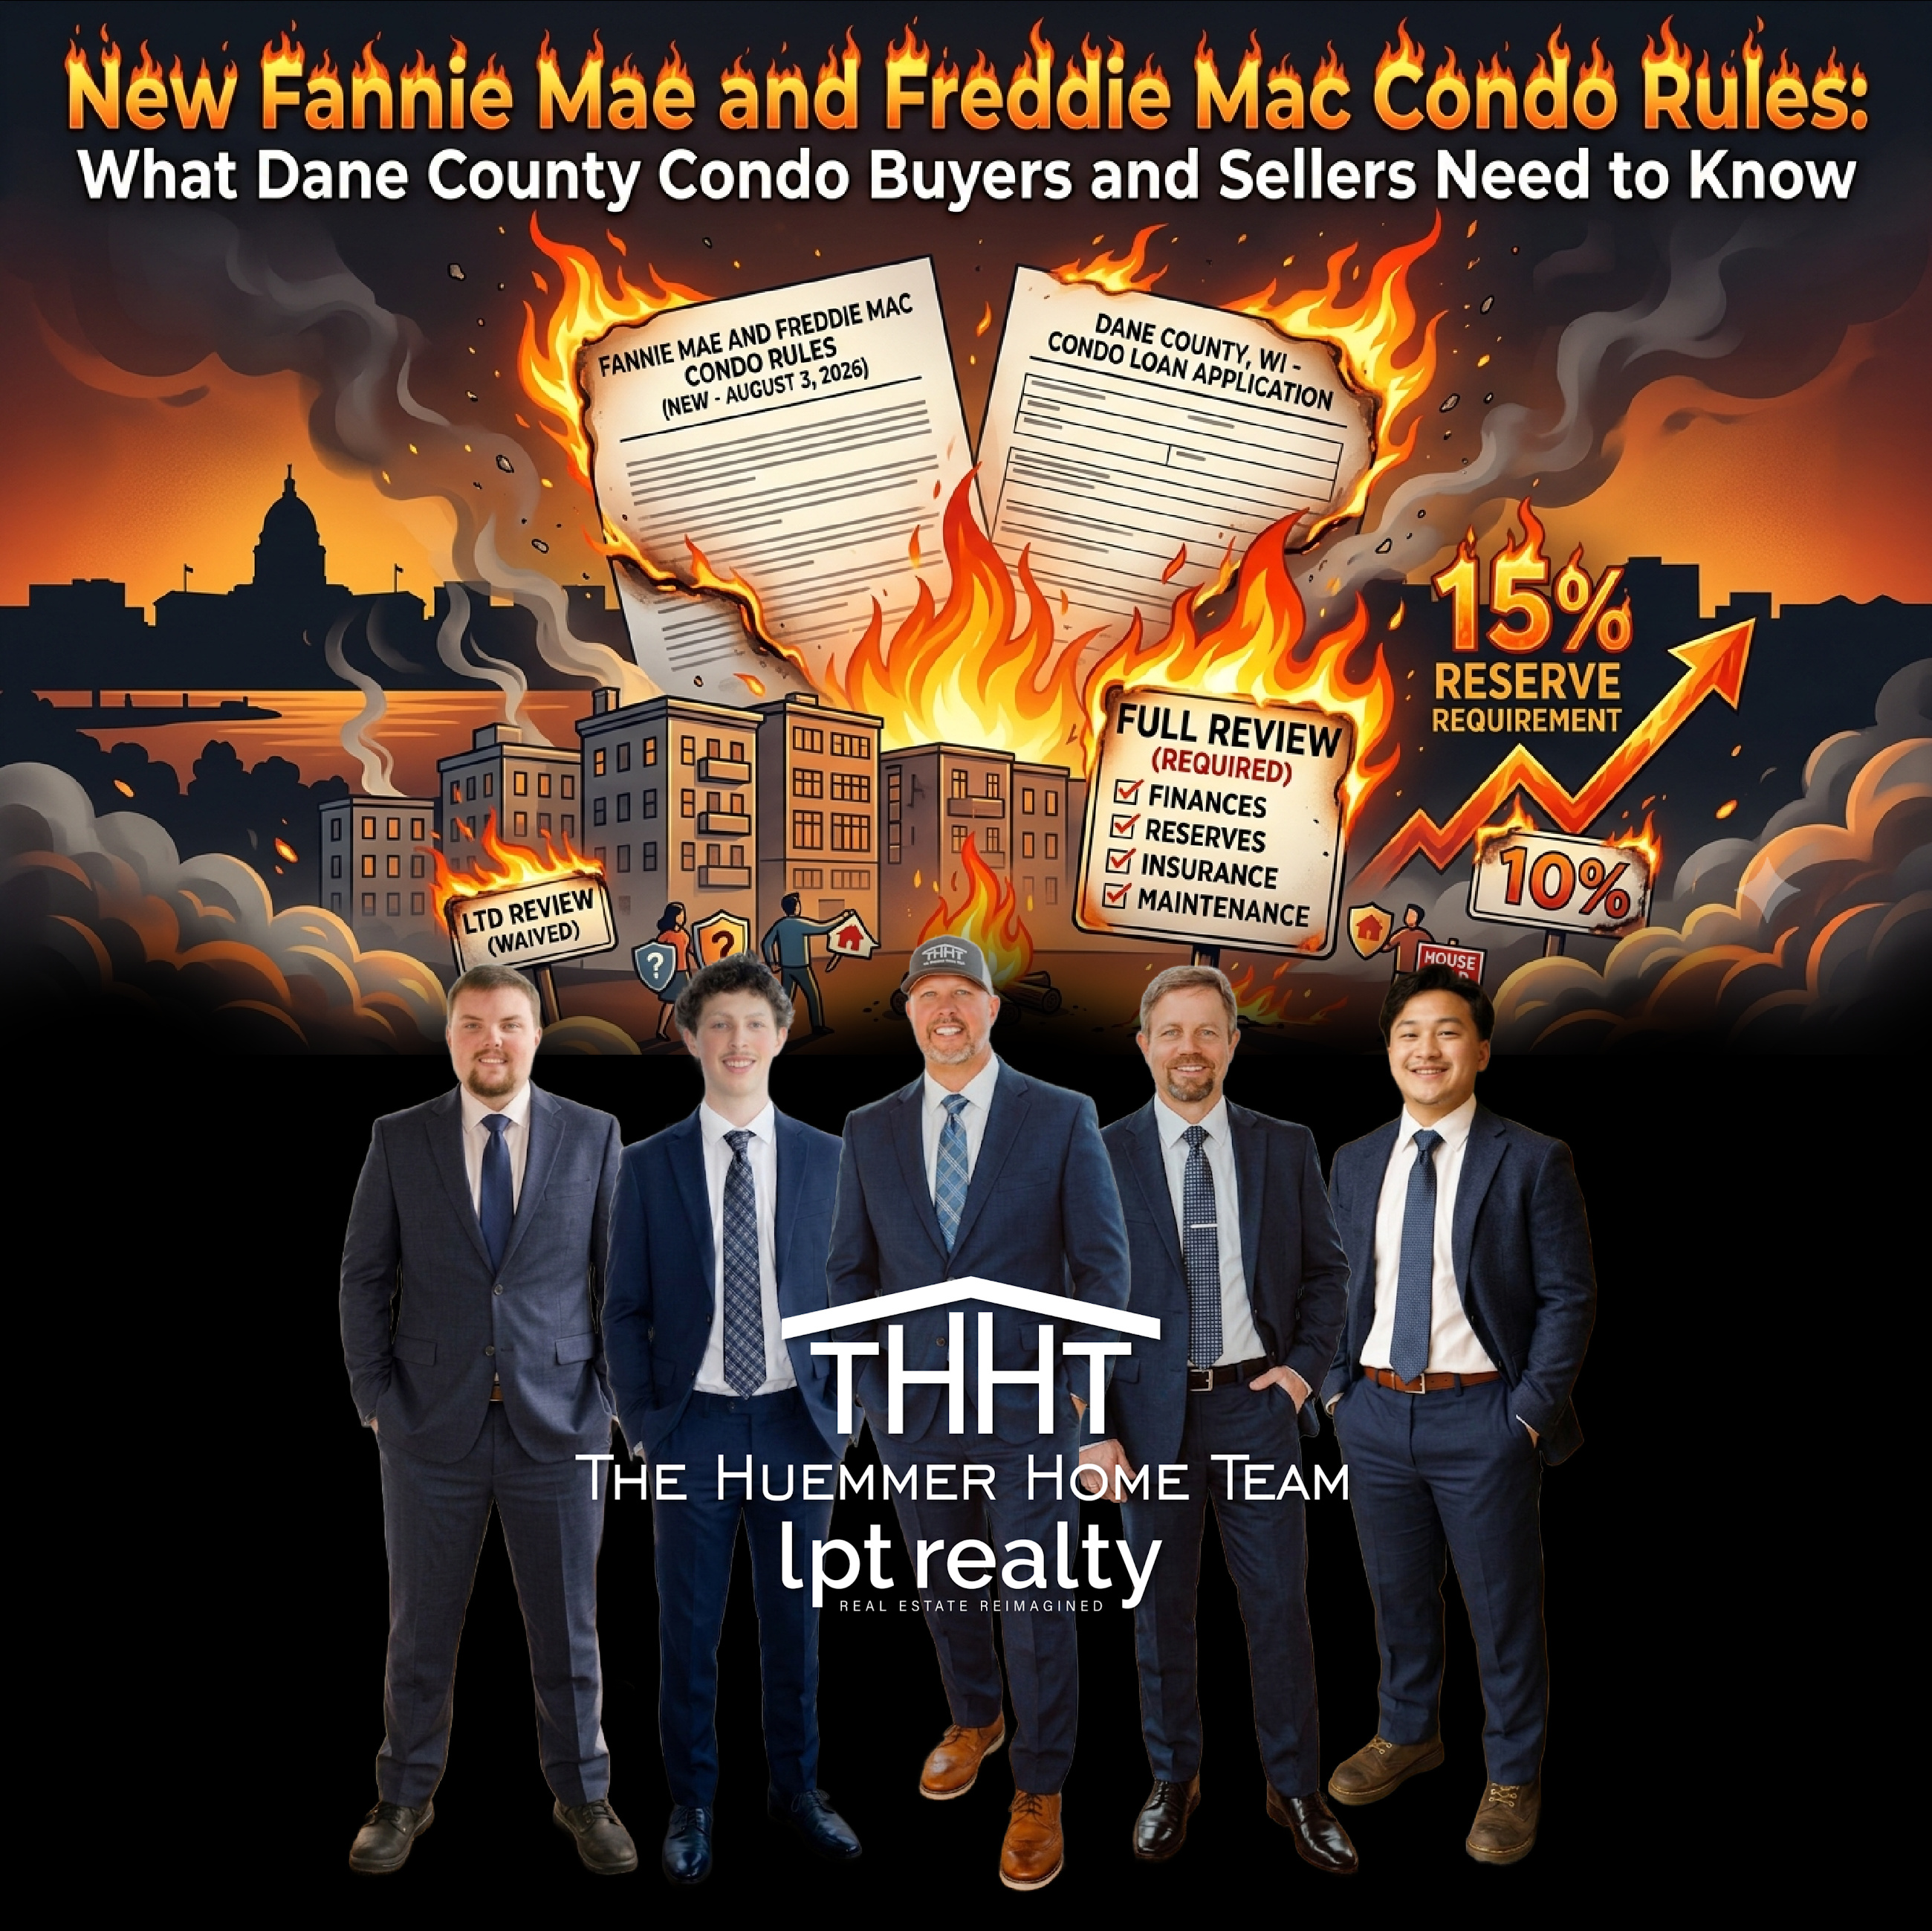
For years, condo projects that looked low-risk could qualify for a "Limited Review" (Fannie Mae) or "Streamlined Review" (Freddie Mac) a faster, lighter-documentation path to loan approval. Roughly 40% of condo mortgage purchases relied on this streamlined pathway.
That option is now gone for most buildings. Unless a project qualifies for a waiver, every condo mortgage now has to go through a "Full Review," which means lenders must dig into:
The condo association's finances
Reserve fund balances
Insurance coverage
The physical condition and maintenance history of the building
Fannie Mae also retired a funding method that let reserve balances run close to zero, and clarified how lenders can use a reserve study to demonstrate adequate reserves.
The Reserve Requirement Is Going Up, Too
Condo associations previously had to budget at least 10% of their annual income toward reserves for future repairs and maintenance. That minimum is rising to 15%. Lenders using the Full Review process must comply with this for loan applications dated on or after January 4, 2027.
For owners, that likely means higher HOA dues as associations work to hit the new threshold. For associations that are underfunded, it could mean a special assessment.
Who's Exempt
Smaller projects catch a break. New and established condo projects with 10 or fewer units may qualify for a waiver from the Full Review requirement, though projects with 5 to 10 units face additional restrictions — particularly if they're part of a larger or master association.
Once a project passes a Full Review, it's recorded as approved in the GSEs' systems. Lenders generally don't have to repeat the full process for every subsequent loan in that building, only the first one triggers the deeper dive.
Why the GSEs Made This Move
This traces directly back to the 2021 Champlain Towers South collapse in Surfside, Florida, which killed 98 people. In the years since, Fannie and Freddie have steadily tightened how they underwrite condo risk, and this is the latest, and most sweeping, round of changes.
Fannie Mae put it plainly in its March announcement: the goal is mitigating the risk of underinsurance and underfunded condo projects, even while acknowledging that rising premiums and limited insurance availability are already squeezing borrowers and associations in some markets.
What This Means If You're Buying
Expect a slower, more paperwork-heavy process. Industry economists are warning of longer application timelines and higher denial rates, especially for buildings that can't quickly produce current financial statements, reserve studies, or inspection records.
A larger down payment won't shield you from the added scrutiny, the building's financial health matters just as much as your own now. Before writing an offer, it's worth asking directly:
What percentage of the annual budget is the association putting toward reserves?
Has the building already passed a Full Review with a lender?
Are there any pending or recent special assessments?
What This Means If You Own or Are Selling
If your association hasn't gotten ahead of the 15% reserve requirement, dues could be climbing before the January 2027 deadline. And if you're planning to sell, a building that hasn't shored up its finances could become harder for buyers to finance with a conventional loan, which shrinks your buyer pool and can put downward pressure on price. It's better to know that now than to find out mid-listing.
The Bottom Line
Some economists argue this is short-term pain for long-term gain, fewer buyers get stuck owning units in poorly maintained, underfunded buildings down the road. Others point out it's landing at a tough time for affordability, when condos have traditionally been the entry point into homeownership for a lot of buyers.
Either way, the rules are in effect now. If you're weighing a condo purchase or sale in the Madison area and want to know how a specific building's financials stack up, reach out, this is exactly the kind of due diligence we walk clients through before they're locked into a contract.
The Huemmer Home Team
LPT Realty
Ryan Huemmer
608-279-7824